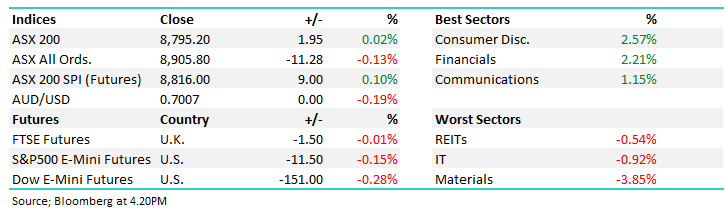
The ASX 200 recovered almost half of its early morning losses, but it still finished the day down 0.4% in a very polarised session. The damage on the index level was again inflicted by miners, with BHP on its own accounting for more than 60% of the index's decline. Fortunately, the banks and broader market were again supportive, with the number of winners just managing to edge the losers despite the main board's decline.
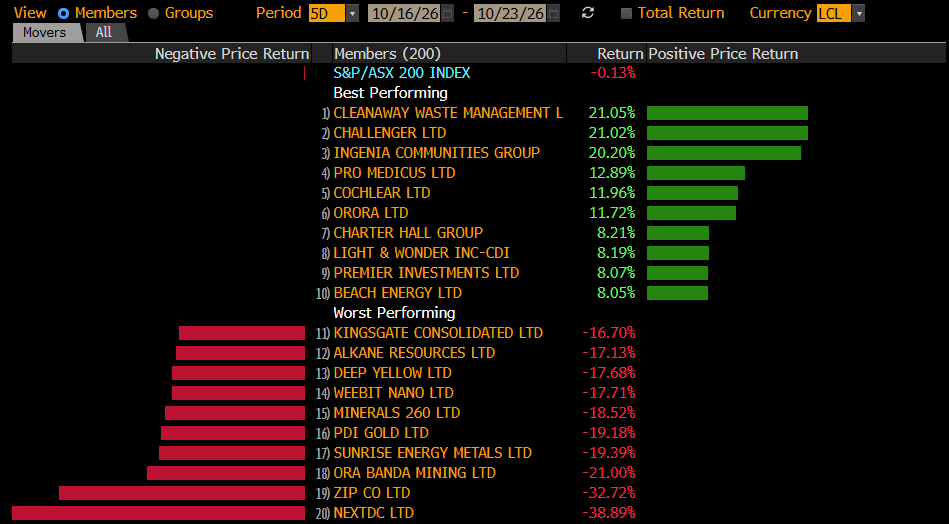
The ASX 200 experienced a choppy Wednesday before rallying into the close, finishing the day up +0.2% - not a bad performance, with BHP Group (-1.6%) and NEXTDC (-42%) combining to take almost 26 points off the index. Fortunately, the banks provided a rare bright spot, with Morgan Stanley estimating that NAB’s planned cull of 2,500 roles could deliver annual cost savings of $400–500 million.
The ASX staged a valiant recovery on Tuesday, clawing back much of its early losses to finish down just 0.3%, despite fewer than 40% of the main board managing to post gains. A soft quarterly update from BHP, and a subsequent -1.6% drop by the Big Australian, contributed 55% of the index's decline on its own, with the more defensive consumer staples and healthcare names stemming the losses.
The ASX 200 ground out a +0.4% gain to start the week, but it wasn’t all plain sailing, with over 50% of the main board closing on the wrong side of the ledger. A +1% average gain by the “Big Four Banks” contributed most to the day's advance, while the miners had a mixed session, with BHP Group (BHP) gaining +0.7% helped by the pick-up in China's growth, which we will look at today, while South32 (S32) -2.6% and PLS Group (PLS) -2.7% were drags on the index. However, Monday was all about takeover fever, a subject MM has written about a few times in 2026.
Thursday's employment data shocked the market and media alike, with employment falling by 39,300 compared to the 20,000 increase economists were expecting. Bad news for the government ahead of next month's Victorian State election, but a welcome reprieve for the RBA, with markets now pricing in only a ~40% chance of another 25bps rate hike before Christmas, although inflation could ultimately force their hand if oil prices keep rising. In 10 days, we get the September CPI (inflation data), which will go a long way in determining the next move on rates.
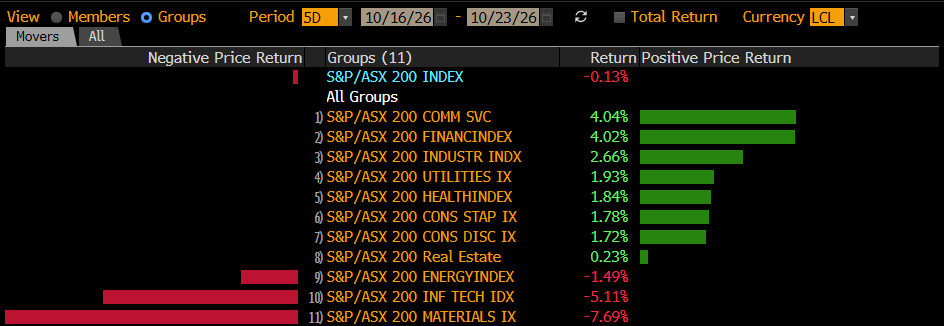
The ASX 200 staged an impressive recovery on Thursday, clawing its way back from an early 1% decline to finish virtually unchanged at 8,720 (-0.1%), as weaker than expected employment data provided a welcome reprieve from the recent interest rate concerns.
The ASX 200 was hit -0.6% on Wednesday for no obvious reason, with renewed selling in the banks the main weight, with the financials accounting for more than 70% of the index's decline. However, weakness was broad-based, with over 70% of the main board closing lower, and the miners adding to the market's woes, which unfortunately look set to extend today.
The ASX fought valiantly on Tuesday to reverse early losses ending the session basically flat. However, it was far from a quiet session on the stock and sector front with AI facing tech stocks whacked, with Megaport (-9.9%) and NEXTDC (-6.6%) enduring sessions to forget.
The ASX 200 big guns started firing on Monday in a rare session of solidarity between the banks and heavyweight miners, the financials and materials combined to add 79-points to the ASX 200, which only closed up 66-points on the day! For a 0.8% gain it was unusual to see almost 50% of the main board close lower, such was the dominance of the likes of BHP (+2.5%) and Westpac (+2.7%).
Shawn reckons the current market reminds him of an old 1980’s song – Reasons to be Cheerful – part 3 (here), hence the title of today’s note – certainly showing his age! Despite the ongoing unsettling news across the newswires, we remain positive on equities here, and today we’ll outline some of the reasons that underpin that view.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
Verication email sent.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
!
Invalid One Time Password
Please check you entered the correct info, please also note there is a 10minute time limit on the One Time Passcode
To reset your password, enter your email address
A link to create a new password will be sent to the email address you have registered to your account.
Market Matters members receive daily market reports, real-time trade alerts, full access to 5 portfolios and dynamic company data.
Choose how you'd like to proceed:
We have a range of membership options to suit your needs and budget, why not join today and get unlimited access to the premium Market Matters service.