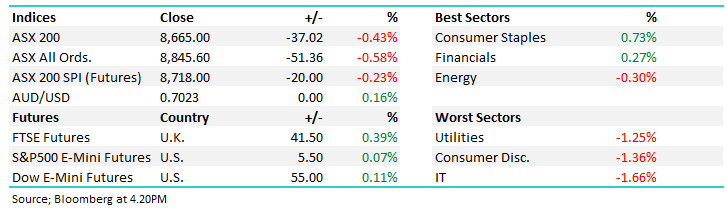
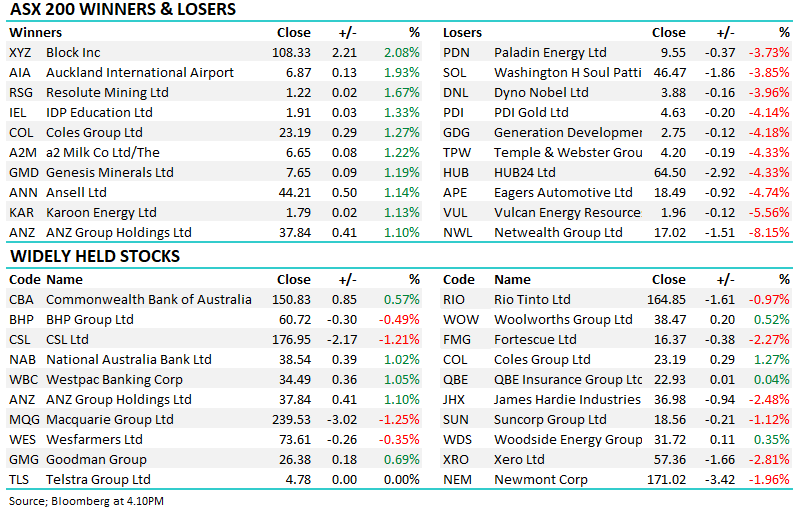
Early weakness saw the ASX 200 make fresh 3-month lows on Thursday following a soft session on Wall Street. The banks and miners finally danced to the same tune, but unfortunately it was a bearish one, which caused ~90% of the day's decline, led by BHP Group (-1.7%), Westpac (-1.8%), and Commonwealth Bank (-0.7%).
The ASX 200 battled to a 0.1% gain on Wednesday, with BHP alone contributing about twice the index’s overall advance from a points perspective, masking underlying weakness in financials. At the stock and sector level, it was almost as if the market had tuned into yesterday’s MM webinar, “Investing in a 5% World,” with investors voting with their feet and compressing the valuations of long-duration growth stocks as bond yields remained elevated.
The ASX 200 experienced a choppy session on Tuesday before eventually closing up +0.3%, taking the index into positive territory for the week. The miners contributed more than 50% of the day's advance, but it was a relatively quiet affair considering the impressive gains in Europe and the US overnight. The tug of war at the pointy end of the market remains fairly evenly balanced, with investors only prepared to buy either the banks or miners on a day-to-day basis, appearing to use the other to fund the purchases.
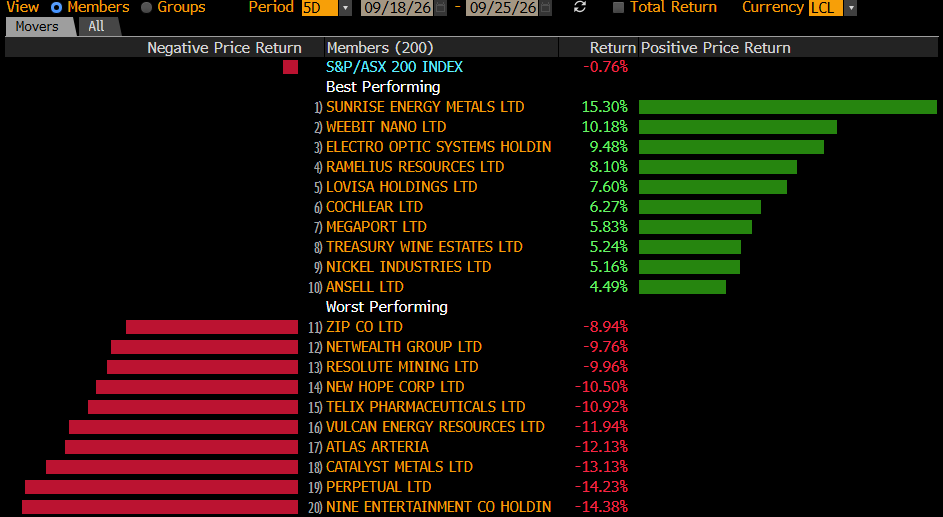
The ASX 200 recovered well from an early 0.6% dip to close flat on Monday, with 45% of the main board managing to advance. Gains by the banks cancelled out losses by the miners, leaving the index evenly balanced into the close. Australian tech stocks, which are primarily software names, continued to underperform, falling 1.6% and extending their decline in 2026 to more than 25%. To put the disappointing performance into perspective, the US software sector is marginally higher for the year.
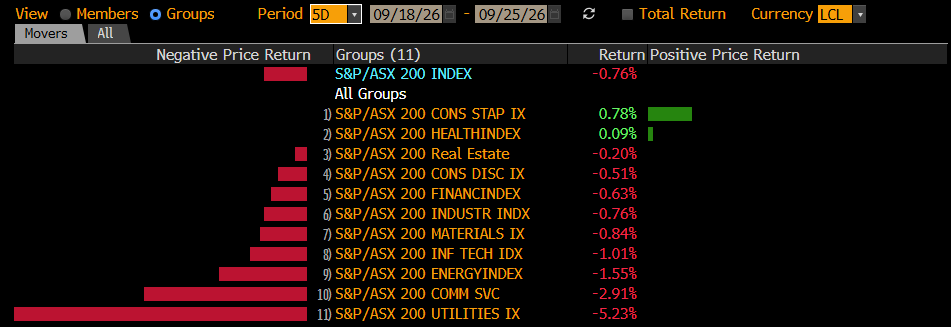
Last week saw the ASX 200 extend its September pullback to -3.8%, taking the total decline from August’s all-time high to almost -7%. The chart below highlights the uncanny similarities with 2022, when the RBA began aggressively tightening monetary policy, and Australia’s 10-year bond yield surged from around 1.5% to 4%, weighing on equity valuations. We’ve been watching with growing interest as the index continues to track the path of 2022’s “bond tantrum” remarkably closely - rising bond yields are the common denominator in both years.
The ASX 200 surprised many on the open yesterday, “gaping up” around 100 points above where it was “supposed” to open, leaving many scratching their heads, but as Shawn rightly pointed out, it's not the first and won't be the last example of market shenanigans on the expiry of the SPI Futures – particularly quarter end expiry. By the close, the local index still managed to finish +0.4% higher, aided by a more than +1% pop by US Futures in their late trade and an average +2% gain by the “Big Four” ASX banks.
The ASX 200 eked out a +0.3% gain ahead of the Fed's rate decision, primarily courtesy of a bounce by the miners, while CBA was the largest drag on the local index, slipping 0.6%. It was encouraging to see the selling pressure across the ASX subside, but with markets becoming increasingly hawkish, we feel investors require some “good news” before they take on more risk with global central banks set to start hiking as elevated oil prices continue to stoke inflation expectations.
The ASX 200 fell another 0.9% on Tuesday, extending September’s decline to 4.5% and pushing the index into negative territory for 2026. The local market has become something of the “ugly duckling” among its global peers, particularly compared with Japan’s Nikkei (+24%) and the US S&P 500 (+12%).
The ASX 200 did well to eke out a modest gain on Monday despite a steady stream of negative news and weakness across global equity markets. Gains in the banks almost exactly offset weakness in the miners as the news continued to weigh on the previously high-flying sector
The oil price is starting to weigh heavily on bond markets and the ASX, but US stocks are taking the geopolitical unrest in its stride, despite markets now pricing in two Fed 0.25% rate hikes by Christmas.
The ASX 200 battled to a 0.1% gain on Wednesday, with BHP alone contributing about twice the index’s overall advance from a points perspective, masking underlying weakness in financials. At the stock and sector level, it was almost as if the market had tuned into yesterday’s MM webinar, “Investing in a 5% World,” with investors voting with their feet and compressing the valuations of long-duration growth stocks as bond yields remained elevated.
The ASX 200 experienced a choppy session on Tuesday before eventually closing up +0.3%, taking the index into positive territory for the week. The miners contributed more than 50% of the day's advance, but it was a relatively quiet affair considering the impressive gains in Europe and the US overnight. The tug of war at the pointy end of the market remains fairly evenly balanced, with investors only prepared to buy either the banks or miners on a day-to-day basis, appearing to use the other to fund the purchases.
The ASX 200 recovered well from an early 0.6% dip to close flat on Monday, with 45% of the main board managing to advance. Gains by the banks cancelled out losses by the miners, leaving the index evenly balanced into the close. Australian tech stocks, which are primarily software names, continued to underperform, falling 1.6% and extending their decline in 2026 to more than 25%. To put the disappointing performance into perspective, the US software sector is marginally higher for the year.
Last week saw the ASX 200 extend its September pullback to -3.8%, taking the total decline from August’s all-time high to almost -7%. The chart below highlights the uncanny similarities with 2022, when the RBA began aggressively tightening monetary policy, and Australia’s 10-year bond yield surged from around 1.5% to 4%, weighing on equity valuations. We’ve been watching with growing interest as the index continues to track the path of 2022’s “bond tantrum” remarkably closely - rising bond yields are the common denominator in both years.
The ASX 200 surprised many on the open yesterday, “gaping up” around 100 points above where it was “supposed” to open, leaving many scratching their heads, but as Shawn rightly pointed out, it's not the first and won't be the last example of market shenanigans on the expiry of the SPI Futures – particularly quarter end expiry. By the close, the local index still managed to finish +0.4% higher, aided by a more than +1% pop by US Futures in their late trade and an average +2% gain by the “Big Four” ASX banks.
The ASX 200 eked out a +0.3% gain ahead of the Fed's rate decision, primarily courtesy of a bounce by the miners, while CBA was the largest drag on the local index, slipping 0.6%. It was encouraging to see the selling pressure across the ASX subside, but with markets becoming increasingly hawkish, we feel investors require some “good news” before they take on more risk with global central banks set to start hiking as elevated oil prices continue to stoke inflation expectations.
The ASX 200 fell another 0.9% on Tuesday, extending September’s decline to 4.5% and pushing the index into negative territory for 2026. The local market has become something of the “ugly duckling” among its global peers, particularly compared with Japan’s Nikkei (+24%) and the US S&P 500 (+12%).
The ASX 200 did well to eke out a modest gain on Monday despite a steady stream of negative news and weakness across global equity markets. Gains in the banks almost exactly offset weakness in the miners as the news continued to weigh on the previously high-flying sector
The oil price is starting to weigh heavily on bond markets and the ASX, but US stocks are taking the geopolitical unrest in its stride, despite markets now pricing in two Fed 0.25% rate hikes by Christmas.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
Verication email sent.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
!
Invalid One Time Password
Please check you entered the correct info, please also note there is a 10minute time limit on the One Time Passcode
To reset your password, enter your email address
A link to create a new password will be sent to the email address you have registered to your account.
Market Matters members receive daily market reports, real-time trade alerts, full access to 5 portfolios and dynamic company data.
Choose how you'd like to proceed:
We have a range of membership options to suit your needs and budget, why not join today and get unlimited access to the premium Market Matters service.