The ASX 200 followed the US futures aggressively lower on Wednesday as it became clear that President Trump and the Republicans had lost control of both the Senate and House; the bookies got it correct.
Yesterday brought us the Melbourne Cup and another 0.25% rate hike by the RBA, taking the cash rate to 4.85%, its highest level in 18 years. The hike was totally expected, but overall the rhetoric from Michele Bullock supported our view that rates will now be on hold well into 2027, with the next move more likely to be a cut.
The ASX 200 fell away on Monday ahead of the RBA and US mid-terms, with the miners and banks, the main contributors to the index's 0.6% decline. The banks slipped despite Westpac (ASX: WBC) advancing +1% following its reasonable FY26 result, despite management warning the next 12–18 months of its UNITE transformation would be challenging - UNITE is WBC’s major, multi-year technology and operational transformation program, designed to simplify how the bank operates, reduce costs and improve customer experience.
The US Tech Sector came under further pressure last week with aggressive pullbacks from the likes of Intel (-24%), Google (-13%), Palantir (-6%), Netflix (-6%), and Meta (-3%) weighing on the indices and general market sentiment. The issue last week wasn’t bond yields, but the latest earnings season exposing the growing cash-flow cost of the AI boom.
Firstly, we have a new data provider now feeding the Market Matters website, with the cut over completed overnight. Further enhancements to come in coming months, which will tie in our expanded data set with some interesting tools to better analysis the market as a whole and improve the navigation around the site.
After opening lower, only to reverse higher on Monday and Tuesday, Wednesday's hot inflation data saw the opposite unfold as the ASX 200 lost an early morning 87-point gain to finish the day mildly lower.
For the second consecutive day, the ASX 200 recovered from early losses to close higher, this time a more impressive +0.5%. Gains were concentrated in the miners, with the materials sector adding 58 points to the index, while financials dragged by 18 points. If the two could just move in the same direction, we’d be trading above 9,000 in the blink of an eye! The miners, and in particular copper names, enjoyed two strong tailwinds on Tuesday.
The ASX 200 reversed from early steep losses to close up +0.2% on Monday, with a +1.7% bounce by the materials sector adding +35 points to the index, more than offsetting weakness in the financials.
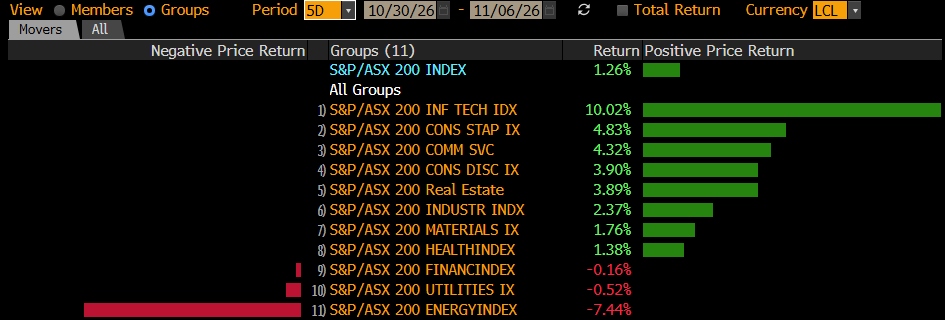
Relative sector performance is very often cyclical, depending on different factors such as bond yields and global economic growth. It may not feel like it, but the ASX 200 Financials and Materials sectors have delivered comparable gains since COVID, rising ~60% and ~50%, respectively, but they’ve followed very different paths.
The ASX 200 followed the US futures aggressively lower on Wednesday as it became clear that President Trump and the Republicans had lost control of both the Senate and House; the bookies got it correct.
Yesterday brought us the Melbourne Cup and another 0.25% rate hike by the RBA, taking the cash rate to 4.85%, its highest level in 18 years. The hike was totally expected, but overall the rhetoric from Michele Bullock supported our view that rates will now be on hold well into 2027, with the next move more likely to be a cut.
The ASX 200 fell away on Monday ahead of the RBA and US mid-terms, with the miners and banks, the main contributors to the index's 0.6% decline. The banks slipped despite Westpac (ASX: WBC) advancing +1% following its reasonable FY26 result, despite management warning the next 12–18 months of its UNITE transformation would be challenging - UNITE is WBC’s major, multi-year technology and operational transformation program, designed to simplify how the bank operates, reduce costs and improve customer experience.
The US Tech Sector came under further pressure last week with aggressive pullbacks from the likes of Intel (-24%), Google (-13%), Palantir (-6%), Netflix (-6%), and Meta (-3%) weighing on the indices and general market sentiment. The issue last week wasn’t bond yields, but the latest earnings season exposing the growing cash-flow cost of the AI boom.
Firstly, we have a new data provider now feeding the Market Matters website, with the cut over completed overnight. Further enhancements to come in coming months, which will tie in our expanded data set with some interesting tools to better analysis the market as a whole and improve the navigation around the site.
After opening lower, only to reverse higher on Monday and Tuesday, Wednesday's hot inflation data saw the opposite unfold as the ASX 200 lost an early morning 87-point gain to finish the day mildly lower.
For the second consecutive day, the ASX 200 recovered from early losses to close higher, this time a more impressive +0.5%. Gains were concentrated in the miners, with the materials sector adding 58 points to the index, while financials dragged by 18 points. If the two could just move in the same direction, we’d be trading above 9,000 in the blink of an eye! The miners, and in particular copper names, enjoyed two strong tailwinds on Tuesday.
The ASX 200 reversed from early steep losses to close up +0.2% on Monday, with a +1.7% bounce by the materials sector adding +35 points to the index, more than offsetting weakness in the financials.
Relative sector performance is very often cyclical, depending on different factors such as bond yields and global economic growth. It may not feel like it, but the ASX 200 Financials and Materials sectors have delivered comparable gains since COVID, rising ~60% and ~50%, respectively, but they’ve followed very different paths.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
Verication email sent.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
!
Invalid One Time Password
Please check you entered the correct info, please also note there is a 10minute time limit on the One Time Passcode
To reset your password, enter your email address
A link to create a new password will be sent to the email address you have registered to your account.
Something went wrong. Please try again in a moment.
You're trying to view member-only content
Market Matters members receive daily market reports, real-time trade alerts, full access to 5 portfolios and dynamic company data.
Choose how you'd like to proceed:
We have a range of membership options to suit your needs and budget, why not join today and get unlimited access to the premium Market Matters service.