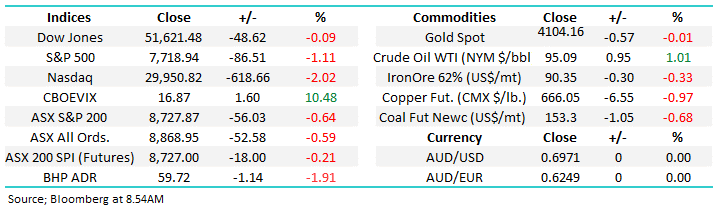
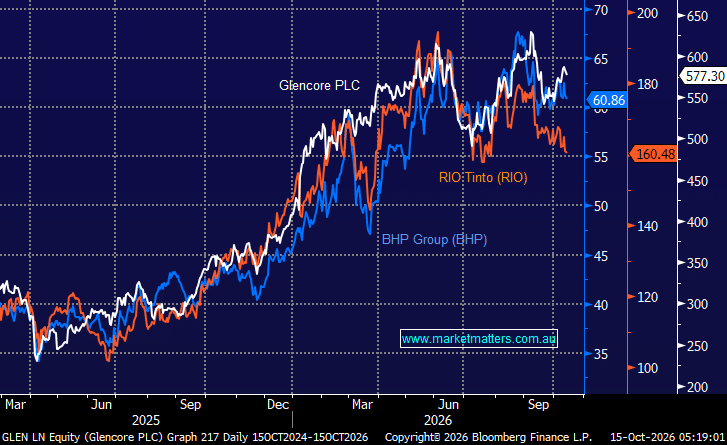
The ASX 200 was hit -0.6% on Wednesday for no obvious reason, with renewed selling in the banks the main weight, with the financials accounting for more than 70% of the index's decline. However, weakness was broad-based, with over 70% of the main board closing lower, and the miners adding to the market's woes, which unfortunately look set to extend today.
The ASX fought valiantly on Tuesday to reverse early losses ending the session basically flat. However, it was far from a quiet session on the stock and sector front with AI facing tech stocks whacked, with Megaport (-9.9%) and NEXTDC (-6.6%) enduring sessions to forget.
The ASX 200 big guns started firing on Monday in a rare session of solidarity between the banks and heavyweight miners, the financials and materials combined to add 79-points to the ASX 200, which only closed up 66-points on the day! For a 0.8% gain it was unusual to see almost 50% of the main board close lower, such was the dominance of the likes of BHP (+2.5%) and Westpac (+2.7%).
Shawn reckons the current market reminds him of an old 1980’s song – Reasons to be Cheerful – part 3 (here), hence the title of today’s note – certainly showing his age! Despite the ongoing unsettling news across the newswires, we remain positive on equities here, and today we’ll outline some of the reasons that underpin that view.
The ASX 200 fell away on Thursday afternoon to close down -0.8%, with weakness in the influential banks and heavyweight miners again driving the index lower while further bargain hunting was evident in the rate-sensitive end of town, although not with any great gusto as would be expected when the index is tumbling toward a fresh 4-month low.
The ASX 200 failed to hold onto its early gains on Wednesday ultimately ending the session down -0.1%, smack in the middle of the day’s trading range, with the influential banks and miners dragging the index lower despite over 60% of the main board closing higher. The rate-sensitive stocks again caught our eye bucking the trend with all major retailers and real estate stocks outperforming the broader index.
The ASX advanced +0.6% on Tuesday on relatively broad based gains with over 60% of the main board closing higher. However, it was the rare combination of strength in both materials and financials that dragged the index higher, contributing ~86% of the days advance from a points perspective. What caught our eye was some buying coming back into some of the consumer facing stocks, ironically just as consumer confidence data plunged towards a 30-year low - there’s nothing quite like the combination of rising interest rates and cost-of-living pressures to squeeze everyday Australians, particularly when the holy grail of household wealth - property prices, are falling at the same time.
The financial press keeps telling us that stocks are expensive and a correction is inevitable, yet US markets remain within 1% of new all-time highs. The chart below tells an interesting story about the two factors pulling the S&P 500 in opposite directions through 2026. Blended forward EPS estimates have surged 35% since year-end, reflecting strong corporate earnings, particularly across AI-related companies, yet the index itself is up only +11.8%.
The ASX 200 was walloped ~2% on the first day of October, registering its biggest daily fall in over six months on broad based selling which saw over 90% of the main board close lower. The selling was compounded by the index breaking to fresh 4-month lows, triggering momentum and trend following systems sell to more, erasing close to $60bn from the index in the process. We believe the aggressive nature of yesterday’s decline came down to three reasons.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
Verication email sent.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
!
Invalid One Time Password
Please check you entered the correct info, please also note there is a 10minute time limit on the One Time Passcode
To reset your password, enter your email address
A link to create a new password will be sent to the email address you have registered to your account.
Market Matters members receive daily market reports, real-time trade alerts, full access to 5 portfolios and dynamic company data.
Choose how you'd like to proceed:
We have a range of membership options to suit your needs and budget, why not join today and get unlimited access to the premium Market Matters service.