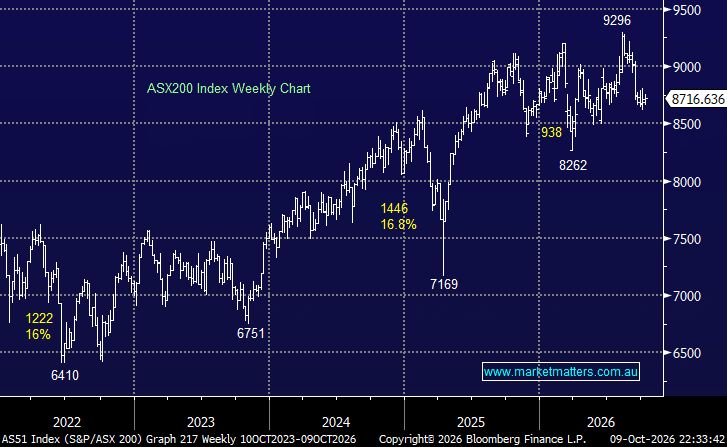
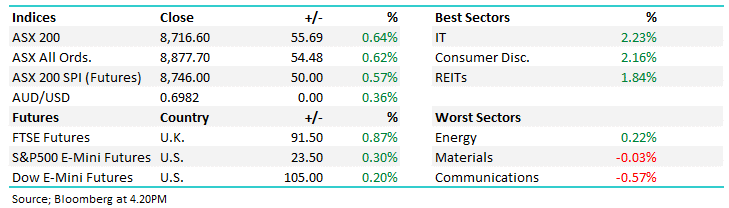
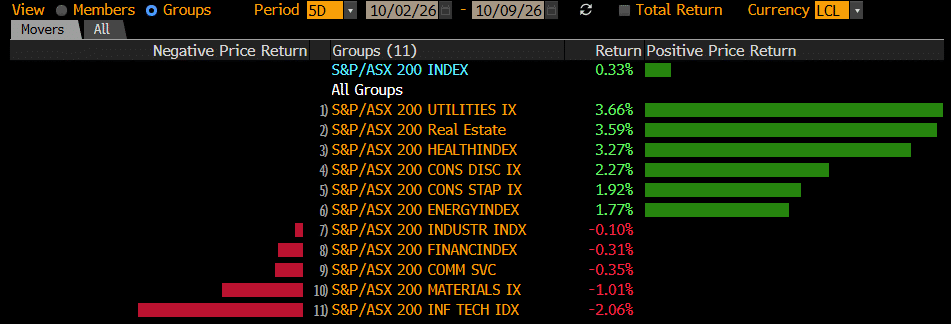
The ASX 200 fell away on Thursday afternoon to close down -0.8%, with weakness in the influential banks and heavyweight miners again driving the index lower while further bargain hunting was evident in the rate-sensitive end of town, although not with any great gusto as would be expected when the index is tumbling toward a fresh 4-month low.
The ASX 200 failed to hold onto its early gains on Wednesday ultimately ending the session down -0.1%, smack in the middle of the day’s trading range, with the influential banks and miners dragging the index lower despite over 60% of the main board closing higher. The rate-sensitive stocks again caught our eye bucking the trend with all major retailers and real estate stocks outperforming the broader index.
The ASX advanced +0.6% on Tuesday on relatively broad based gains with over 60% of the main board closing higher. However, it was the rare combination of strength in both materials and financials that dragged the index higher, contributing ~86% of the days advance from a points perspective. What caught our eye was some buying coming back into some of the consumer facing stocks, ironically just as consumer confidence data plunged towards a 30-year low - there’s nothing quite like the combination of rising interest rates and cost-of-living pressures to squeeze everyday Australians, particularly when the holy grail of household wealth - property prices, are falling at the same time.
The financial press keeps telling us that stocks are expensive and a correction is inevitable, yet US markets remain within 1% of new all-time highs. The chart below tells an interesting story about the two factors pulling the S&P 500 in opposite directions through 2026. Blended forward EPS estimates have surged 35% since year-end, reflecting strong corporate earnings, particularly across AI-related companies, yet the index itself is up only +11.8%.
The ASX 200 was walloped ~2% on the first day of October, registering its biggest daily fall in over six months on broad based selling which saw over 90% of the main board close lower. The selling was compounded by the index breaking to fresh 4-month lows, triggering momentum and trend following systems sell to more, erasing close to $60bn from the index in the process. We believe the aggressive nature of yesterday’s decline came down to three reasons.
The ASX 200 rebounded 0.3% following yesterday’s 0.25% RBA rate hike, helped by Governor Michele Bullock’s comments proving less hawkish than many had feared. The cash rate is now at a 15-year high of 4.60%, but we found the market's reaction encouraging: the A$ fell to a two-month low and credit markets pared back expectations for further tightening, with only around a 60% chance of one more hike before Christmas now priced in.
The ASX 200 found support from some of 2026’s most unloved sectors on Monday, with some book-squaring seemingly at play ahead of today’s widely expected 0.25% RBA rate hike, priced at a 93% probability by Monday’s close. However, as has been the case of late, the session was more about switching than outright buying or selling, leaving the index just +0.2% higher as Financials added 33 points, almost entirely offset by a 31-point drag from Materials.
The Fed and RBA have taken different paths in the last few years, but both have ultimately started tightening again. The Fed began 2024 with rates at 5.25%-5.5%, cut aggressively by a total of 175bps to 3.5%-3.75% by December 2025, then paused as inflation pressures returned before hiking 25bps to 3.75%-4.0% earlier this month. In contrast, the RBA waited until February 2025 to start cutting and delivered just 75bps of easing, taking the cash rate from 4.35% to a low of 3.60% by August 2025. It's been hard work of late for local investors with higher interest rates and lower earnings growth:
Early weakness saw the ASX 200 make fresh 3-month lows on Thursday following a soft session on Wall Street. The banks and miners finally danced to the same tune, but unfortunately it was a bearish one, which caused ~90% of the day's decline, led by BHP Group (-1.7%), Westpac (-1.8%), and Commonwealth Bank (-0.7%).
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
Verication email sent.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
!
Invalid One Time Password
Please check you entered the correct info, please also note there is a 10minute time limit on the One Time Passcode
To reset your password, enter your email address
A link to create a new password will be sent to the email address you have registered to your account.
Market Matters members receive daily market reports, real-time trade alerts, full access to 5 portfolios and dynamic company data.
Choose how you'd like to proceed:
We have a range of membership options to suit your needs and budget, why not join today and get unlimited access to the premium Market Matters service.